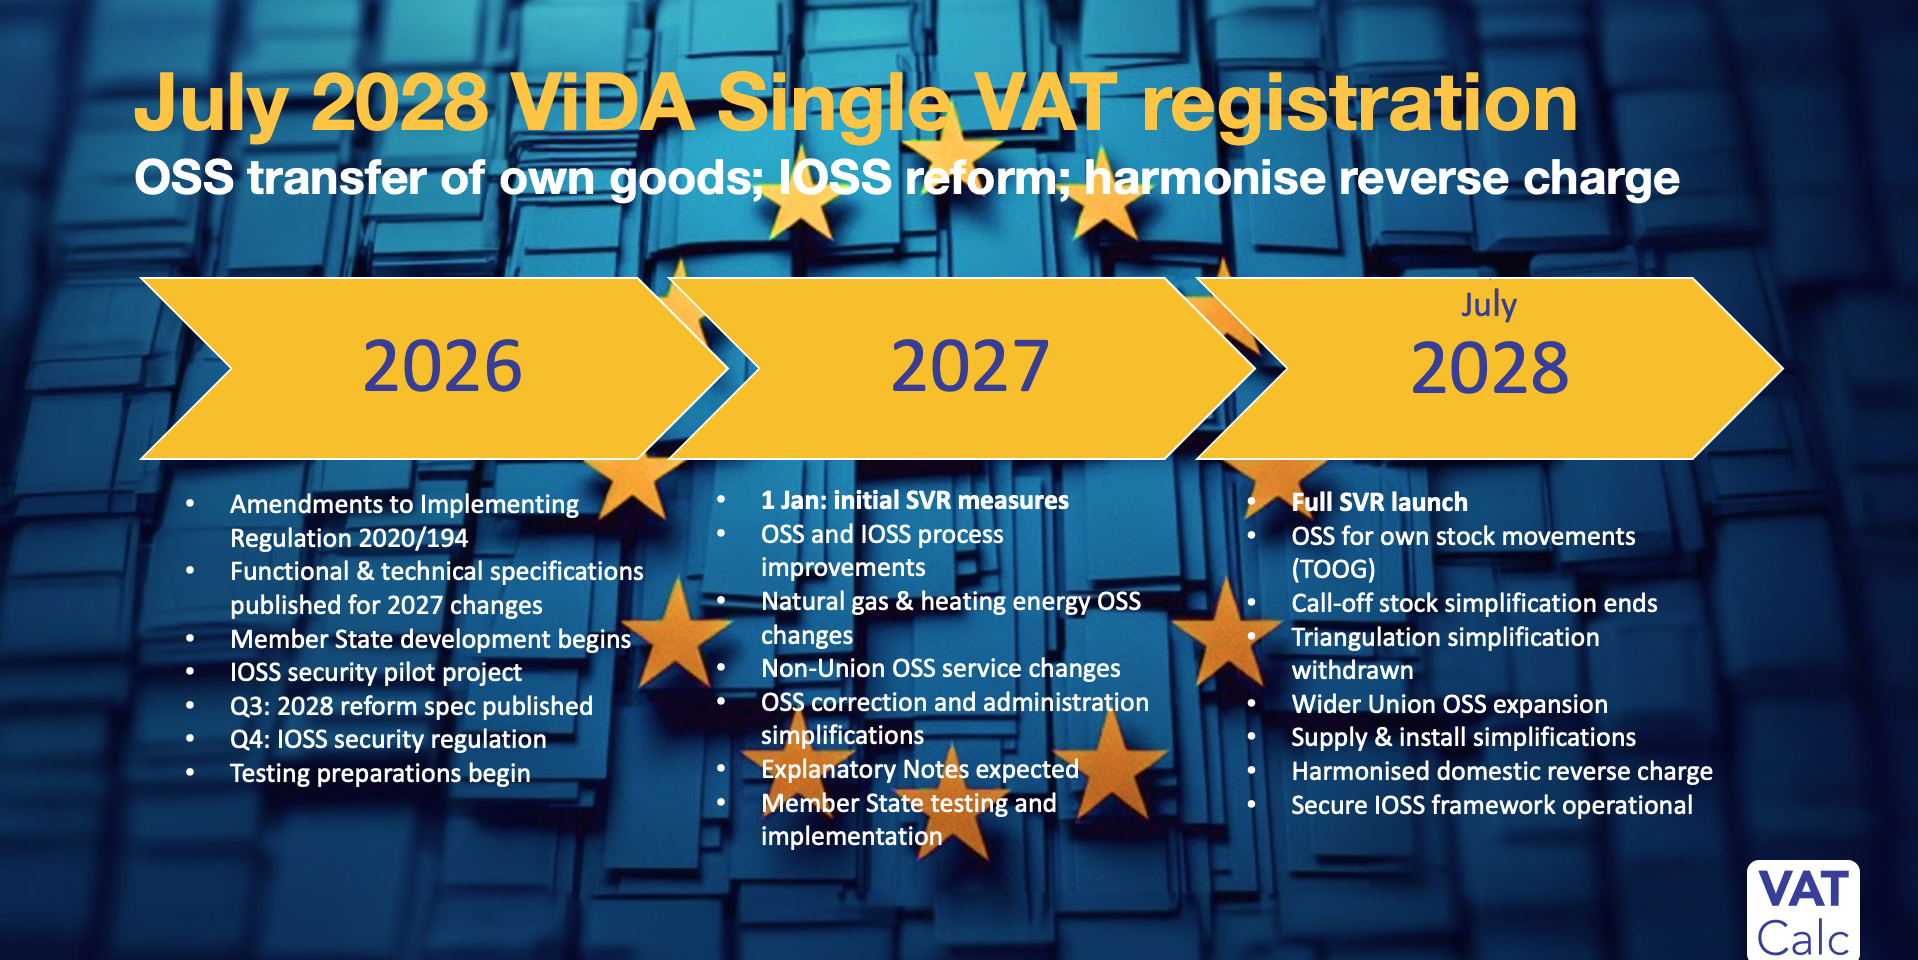
July 2028 extension of OSS return (SVR) and IOSS reforms
SVR: Cross-border transfer of own goods TOGG; harmonisation of domestic reverse charge
19 Aug: updated SVR 2027 changes explanatory notes issued covering changes to OSS and IOSS
27 July 2026: EC adopts implementing regulations for SVR reforms in Jan 2027 and July 2028. It also updates the OSS guide for Jan 2027 reforms (full revision due in 2027 for the 2028 changes.

20 May: Commission’s EU VAT in the Digital Age (ViDA) work programme provided an update on legislative, technical and operational work underway. The first Explanatory Notes to complete by early 2027. The focus is preliminary 1 January 2027 changes.
There are now two SVR channels: extension of the One Stop Shop (OSS); and Securing Import One Stop Shop IOSS.
1. Single VAT Registration OSS extension timetable:
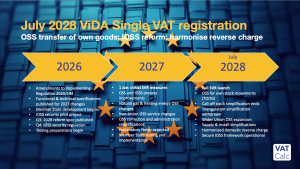
Q3 2026
The Commission has adopted in July amendments to Commission Implementing Regulation (EU) 2020/194. These changes will introduce legal clarifications and operational improvements required for the first phase of the SVR reforms that become effective on 1 January 2027.
The first Explanatory Notes were published in July 2026 covering the technical changes taking effect on 1 January 2027. A substantially revised version will follow ahead of the wider Single VAT Registration reforms applying from 1 July 2028.
Q4 2026
A separate implementing regulation aimed at securing IOSS numbers is currently planned for adoption (see below). The objective is to reduce misuse and fraud involving IOSS identification numbers used in low-value import transactions.
Q1 2027
The Commission is expected to publish revised functional and technical specifications covering the much larger reform package scheduled for 1 July 2028.
Member States will begin assessing the technical development requirements following publication.
1st January 2027
The Commission Explanatory Notes covers the first phase changes in 2027 for the 2028 Single VAT Registration framework. EU Member States are expected to complete national implementation of the first phase of the reforms applying from 1 January 2027.
These are primarily technical and administrative improvements to the existing OSS, non-Union OSS and IOSS schemes, including process simplifications, correction mechanisms and legislative clarifications:
- Supplies of natural gas, heating and cooling energy cross-border are deemed distance sales as so may be reported in OSS.
- The rules on the calculation of €10,000 intra-community distance sales of goods and TBE (telecoms; broadcast; electronic) services may only include supplies from the country of establishment. But with OSS option for the place of supply to be determined in accordance with Article 33 (Member State of final destination)
- Harmonise minor differences on timing of chargeable events in the Union and non-Union schemes.
- Clarify that the non-Union scheme covers B2C services provided in the EU to any customer and not only to EU established customers
- IOSS administration changes
1 July 2028 reforms
The most significant structural changes under ViDA’s Single VAT Registration pillar will take effect from 1 July 2028. These include:
- Extension of the Union OSS scheme to additional transactions
- Inclusion of transfers of own goods TOOG within OSS reporting
- Removal of the call-off stock simplification
- Elimination of triangulation reporting requirements
- New EU-wide registration data exchange layer.
- Enhanced identification logic for non-established traders.
- Streamlined lifecycle management for OSS/SVR accounts.
Together these reforms are intended to substantially reduce the need for businesses to obtain and maintain multiple VAT registrations throughout the EU.
The EC is also considering improvements to the public VIES service to assist businesses in validating traders’ VAT registration status as the Single VAT Registration reforms expand.
2. IOSS security initiative moves forward
Alongside the wider SVR reforms, the Commission continues to develop measures aimed at securing the Import One Stop Shop regime.
A dedicated implementing regulation is expected in late 2026, supported by pilot projects examining mechanisms to reduce misuse of IOSS identification numbers:
- Early 2026 – Implementation phase begins, including IT development.
- Rest of 2026 – Live operation of the Secure IOSS pilot.
- End Q1 2027 – Adoption of the related Commission Implementing Regulation in SCAC.
- Q2 2027 – Q2 2028 – Full implementation: specifications, development, integration and testing.
The Commission is also evaluating fast-track validation options that could provide real-time verification of IOSS numbers during import processing.
This reflects growing concern amongst Member States regarding fraudulent use of IOSS registrations and the integrity of low-value import declarations.
SVR outstanding technical and policy tensions remain
Despite the increasingly detailed implementation timetable, a number of difficult policy and operational questions remain unresolved.
One continuing area of uncertainty is the interaction between the SME exemption regime and IOSS. Current Commission guidance suggests the two regimes are mutually exclusive, potentially limiting flexibility for smaller cross-border sellers.
There is also continued ambiguity regarding the €10,000 EU distance selling threshold where businesses hold inventory across multiple Member States. Businesses continue to seek clarity on how stock movements affect threshold calculations and reporting obligations.
The treatment of fixed establishments remains politically sensitive. ViDA continues to support the principle that merely holding stock in a Member State should not automatically create a fixed establishment. However, several tax authorities remain cautious about adopting this interpretation.
Additional areas where guidance is still awaited include:
- Taxable event timing under the revised OSS and non-Union OSS schemes
- The interaction between OSS and SME regimes
- Harmonisation of tax representative requirements
- Treatment of fixed establishments holding stock
- Differing interpretations of the “Group of Four” deemed supplier rules
- Whether certain 2028 simplifications will be mandatory or optional
- Transitional arrangements between the 2027 and 2028 implementation phases
While the legal framework is now largely settled, many of these practical questions will need to be addressed through the forthcoming explanatory notes and technical guidance.
Harmonisation of domestic reverse charge rules
The proposed harmonisation of the non-resident B2B domestic reverse charge (Article 194) rules will go ahead, but it has been modified to give member states some flexibility. Member states will be required ‘shall’ apply the reverse charge when a non-resident supplier supplies a customer that is VAT registered in the country. But Member States are given flexibility if they wish to adopt different rules to apply the reverse charge. For instance, applying the reverse charge only when the customer is established in the Member State that the VAT is due. Margin scheme supplies and works of art are excluded. Such transactions must be disclosed on the ESL.
Standard Audit File and OSS audit reforms
The Commission has also confirmed further work on audit and control procedures for the OSS and IOSS regimes.
This includes:
- A second amendment to Implementing Regulation (EU) 2020/194
- Development of a Standard Audit File covering OSS special schemes
- Updated guidance for Member States on auditing OSS and IOSS transactions
- Harmonised administrative cooperation procedures
These initiatives are intended to improve consistency across Member States as OSS reporting volumes continue to grow.

VAT Filer reporting for OSS extension
VAT Calc’s global returns reporting app, ‘VAT Filer’, has been developed with the EU’s VAT in the Digital Age reforms in full focus, the extension of OSS for own stocks and other supplies. And since VAT Filer is built on the same single platform as our VAT Calculator tax engine product, there is full reconciliation on VAT return reporting.
EU VAT in the Digital Age reforms
| EU VAT in the Digital Age | |
| 3 pillars to improve efficiency of VAT for all and reduce fraud | |
| 1. Digital Reporting Requirements; e-invoicing | Jul 2030-35: Mandatory digital reporting of intra-community transactions; obligation to be able to issue and receive intra-community e-invoices; member states free to impose own e-invoicing or real-time reporting but most conform to EU e-invoice standard EN 16931 |
| Read more about EU Digital Reporting Requirements (DRR) | |
| Structured e-invoices mandated for intra-community supplies | |
| EC Sales lists replaced by Digital Reporting Requirements | |
| 10-day e-invoicing deadline for intra-community sales | |
| 5-day e-reporting time limit intra-community purchases | |
| Withdrawal of EU permission requirements for e-invoicing | |
| Central VIES database launch | |
| 2 Platform economy | Jul 2028 / Jan 2030: Travel & accommodation sharing platforms to become deemed supplier / liable to users' VAT. New definitions of the roles of providers, users and platforms to avoid double and no-taxation (voluntary Jul 2028) |
| Read more - Travel & accommodation platforms deemed suppliers for EU VAT | |
| 3 Single VAT Registration; extension of OSS | July 2028: Following the 1 July 2021 introduction of the One Stop-Shop (OSS), extended to cover movement of own stocks prior to cross-border B2C to reduce the foreign, non-resident VAT registrations & returns. Plus to movements of own stock with ending of 'call-off' stock burden |
| January 2027 initial changes | |
| Transfer of own goods OSS extension | |
| Call-off stock VAT simplification ends | |
| Harmonisation of B2B Reverse Charge rules | |
| Creation of Single VAT Registration identiy | |
| Securing IOSS (Mar 2028) | |