Updated 13 November 2026 Brazil is entering the next major phase of its consumption tax reforms, with the introduction of the new federal CBS VAT from January 2027 and the progressive replacement of state and municipal taxes through 2032.
On 11 November 2026, Brazil’s Federal Revenue Service (Receita Federal) confirmed its latest implementation roadmap, including revised regulations, expanded taxpayer testing, digital tax assessments and a new compliance support programme for 2027.
2 November 2026 – Brazil’s Federal Court of Accounts (TCU) has approved an 11.3% reference rate for the 2027 federal Consumption Tax on Goods and Services (CBS)
Brazil Split Payments will start in 2027, initially on a voluntary basis for B2B transactions. There are separate plans for VAT on financial services.
Brazil’s new dual VAT system
The reform introduces three principal taxes:
- CBS (Contribuição sobre Bens e Serviços): Federal VAT replacing PIS and COFINS from January 2027.
- IBS (Imposto sobre Bens e Serviços): State and municipal VAT progressively replacing ICMS and ISS between 2029 and 2033.
- IS (Imposto Seletivo): A selective tax on specified goods and services, including products considered harmful to health or the environment.
The new VAT system is based on destination taxation, broader input tax credit recovery and a simplified structure of tax rates and exemptions.
However, businesses will face several years of parallel tax regimes as the existing and replacement taxes operate alongside one another.
Brazil VAT implementation timetable 2027–2032
|
Year |
CBS federal VAT |
IBS state and municipal VAT |
Other changes |
|---|---|---|---|
|
2027 |
CBS replaces PIS and COFINS |
Transitional IBS rate of 0.1% |
Selective Tax introduced; IPI generally reduced to zero |
|
2028 |
CBS continues |
IBS remains at 0.1% |
Further operational transition |
|
2029 |
CBS operational |
IBS replaces 10% of ICMS/ISS |
ICMS/ISS reduced to 90% |
|
2030 |
CBS operational |
IBS replaces 20% of ICMS/ISS |
ICMS/ISS reduced to 80% |
|
2031 |
CBS operational |
IBS replaces 30% of ICMS/ISS |
ICMS/ISS reduced to 70% |
|
2032 |
CBS operational |
IBS replaces 40% of ICMS/ISS |
ICMS/ISS reduced to 60% |
|
2033 |
CBS fully operational |
IBS fully implemented |
ICMS and ISS abolished |
The percentages shown for 2029–2032 represent the statutory proportions used during the transition, not the final IBS tax rates.
2027: CBS implementation
From 1 January 2027, CBS replaces the federal PIS and COFINS taxes. Its applicable rate will be subject to a temporary reduction of 0.1 percentage points during 2027 and 2028.
The IBS transitional rate remains 0.1%, divided between state and municipal components.
The Selective Tax also takes effect, while federal IPI rates are generally reduced to zero, subject to exceptions.
2029–2032: Progressive IBS implementation
The transition to IBS begins in earnest in 2029, when existing ICMS and ISS liabilities start to be progressively reduced.
Businesses must calculate and account for both the new IBS and the remaining legacy taxes throughout this period. This will create substantial challenges for tax determination, electronic invoicing, input tax credits and accounting reconciliations.
November 2026: Brazil confirms next implementation milestones
The 11 November 2026 revised roadmap ahead of the January 2027 implementation is as follows:
|
Date |
Implementation milestone |
|---|---|
|
November 2026 |
Revised CBS and IBS Regulation 2.0 expected |
|
November 2026 |
Pilot environment scheduled to open to all taxpayers |
|
November 2026 |
Technical specifications for assisted-assessment adjustments |
|
Early December 2026 |
Further CBS and IBS regulations |
|
December 2026 |
Prototype of the digital assessment adjustment module |
|
March 2027 |
Deferred documentation requirements for certain situations |
The announcement also confirmed plans for further legislation addressing payment-linked VAT credits and split payments.
These measures are intended to support the transition to a system in which tax collection and credit recovery become more closely connected to actual payments.
Brazil introduces digital VAT assessments
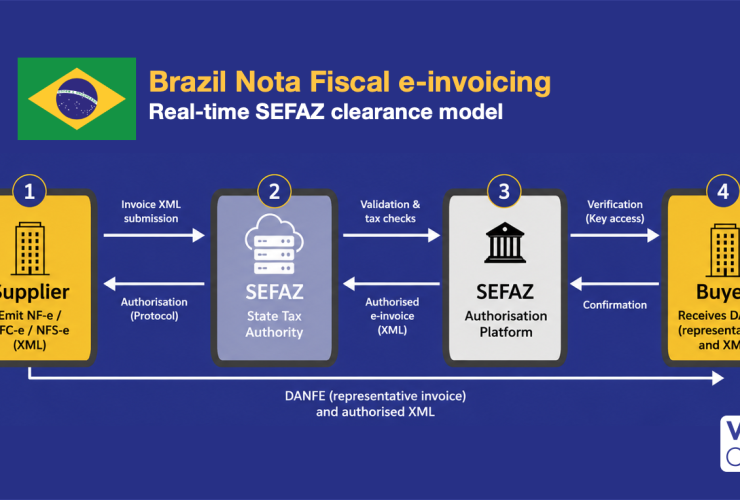
A significant feature of the reform is the introduction of assisted VAT assessments, under which Receita Federal uses electronic fiscal documents and transaction data to calculate CBS liabilities and credits.
In October 2026, the tax authority released updated APIs allowing taxpayers to retrieve information on assessed CBS debits and credits.
The system is designed to provide greater visibility over tax liabilities, credit entitlements and adjustments.
However, businesses remain responsible for ensuring that their underlying transactions have been correctly classified and taxed.
The digitalisation of VAT assessments therefore increases the importance of accurate tax determination, master data and reconciliation between internal accounting records and tax authority calculations.
Brazil announces 2027 VAT compliance support programme
Receita Federal has also outlined a compliance programme for 2027 to help businesses adapt to the new requirements.
The programme includes assistance with electronic fiscal documentation, preventive correction of errors and guidance on the new tax rules.
The authority has indicated that taxpayers acting in good faith, providing complete information and following appropriate accounting practices may avoid penalties where genuine uncertainty arises during the transition.
Further details of the programme’s eligibility conditions and operational procedures are expected.
What businesses must prepare for
Brazil’s reforms require much more than updating VAT rates.
Businesses will need to adapt their ERP and tax determination systems to manage CBS, IBS and legacy taxes simultaneously. Electronic fiscal documents must support the new tax classifications, while accounting systems must reconcile transaction-level liabilities, input tax credits and tax authority assessments.
The progressive introduction of payment-linked credits and split payments could also have significant implications for working capital and VAT recovery.
Although the reforms are intended to simplify Brazil’s consumption tax system, the transition through 2032 will temporarily increase compliance complexity.