VAT wins the policy debate in IMF working paper
The International Monetary Fund (IMF) has published a comprehensive working paper review of how governments should tax the rapidly expanding market for cross-border digital services.

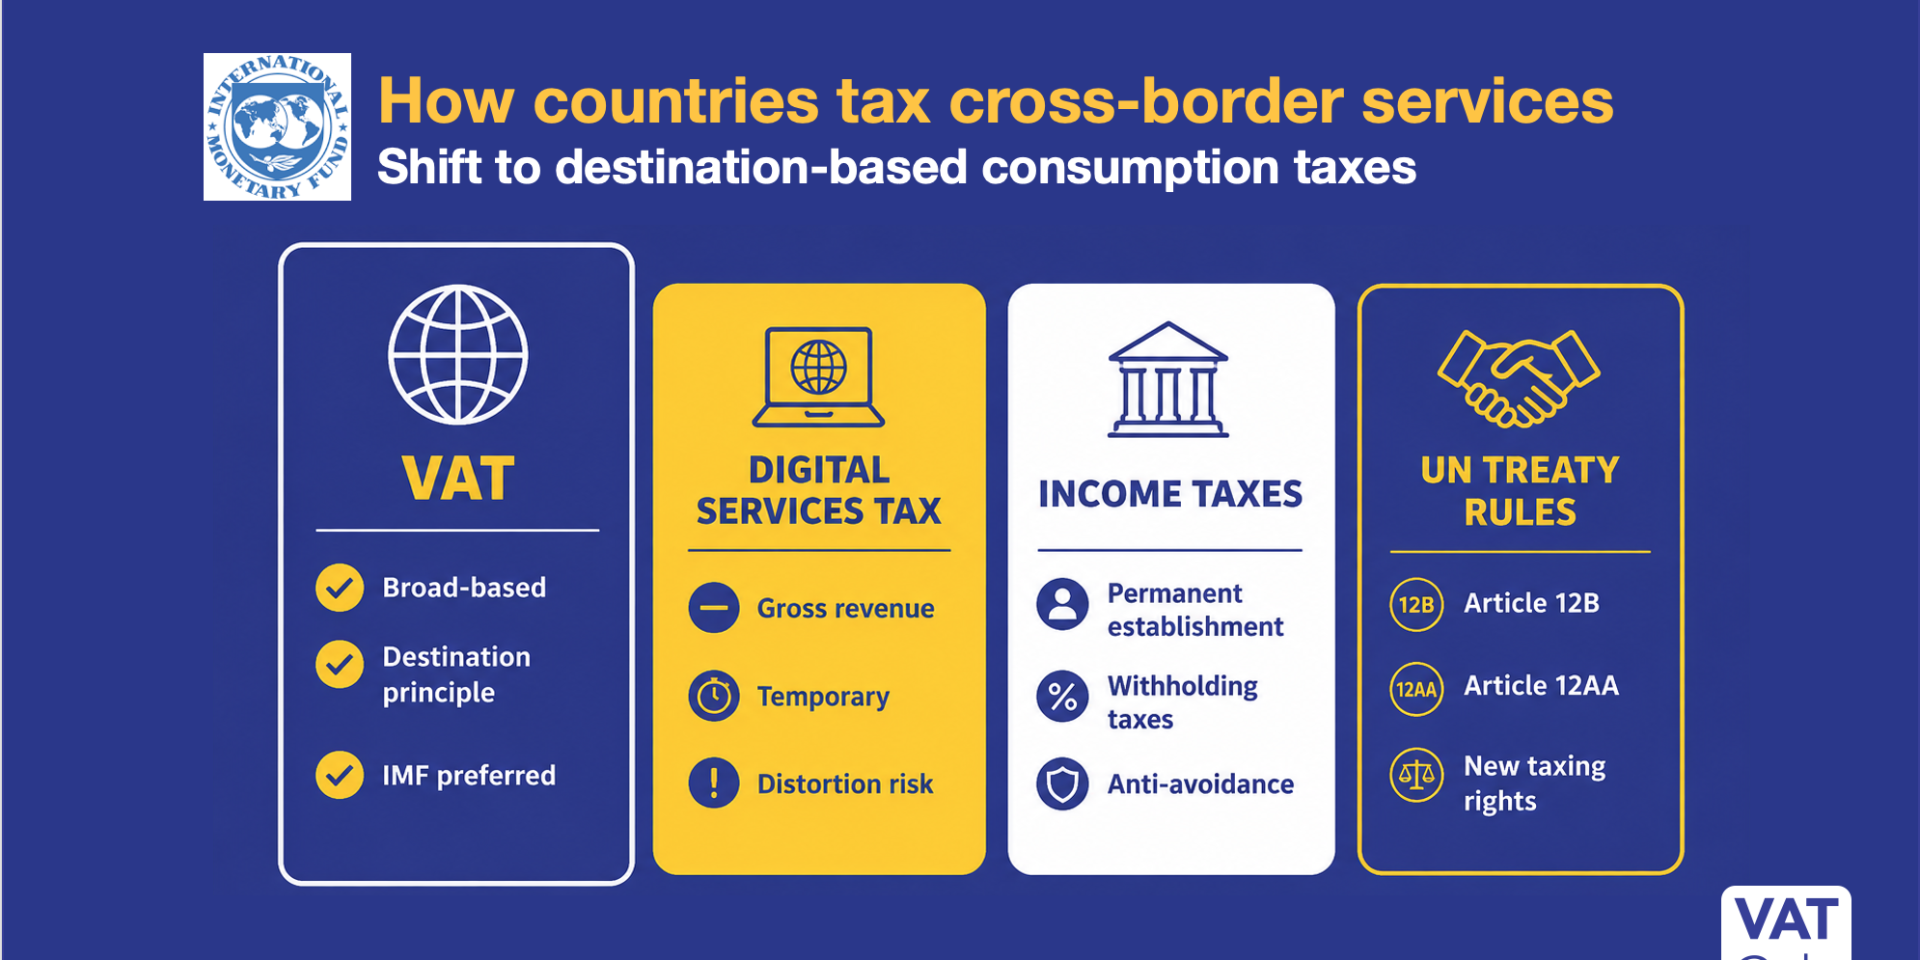
Covering VAT on digital services, Digital Services Taxes (DSTs), withholding taxes and new international tax treaty proposals, the report reaches a clear conclusion: destination-based VAT remains the most effective and least distortionary way to tax digital services.
As services become increasingly digital and can be supplied remotely without any physical presence, governments are searching for ways to ensure tax follows consumption rather than corporate location.
Digital services upending global trade
Cross-border services now account for more than a quarter of world trade, with cloud computing, software, streaming, consulting and other digitally delivered services continuing to outpace traditional sectors. This growth is exposing the limitations of international tax rules that were largely designed around physical establishments and tangible goods.
The IMF argues that modern tax systems must adapt to this reality without creating unnecessary complexity or distorting international trade.
VAT is the starting point
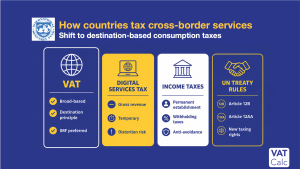
For VAT professionals, the report reinforces the direction governments have already been taking. Modern VAT systems should ensure imported digital services are taxed where they are consumed through:
- destination-based place of supply rules
- reverse charge mechanisms for B2B services
- simplified VAT registration for overseas suppliers
- digital platform collection models – deemed supplier.
According to the IMF, the challenge today is no longer the policy principle but effective implementation.
DSTs remain a contentious temporary compromise
The report is considerably more cautious on Digital Services Taxes.
While recognising that DSTs were introduced because multinational digital businesses could generate significant revenues without a taxable presence, the IMF concludes that these taxes remain inherently distortionary because they tax turnover rather than profits.
Its research suggests DSTs reduce digital services imports, indicating that much of the tax burden is ultimately passed onto business customers and consumers rather than the multinational companies they target.
Nevertheless, with OECD Pillar One still stalled, DSTs are likely to remain part of many countries’ tax systems for the foreseeable future.
International Tax Rules Continue to Evolve
The IMF also highlights important developments within the United Nations.
New treaty provisions, including Articles 12B and 12AA, would allow countries to tax income from remote digital and cross-border services without relying solely on traditional permanent establishment rules. These proposals could become increasingly significant as international tax reform gradually shifts towards the UN framework.
For multinational businesses, this makes robust VAT determination, digital reporting and cross-border compliance more important than ever.
Europe Digital Services Taxes (DST)
| Country | Status | Rate | Annual sales threshold | Scope | |
| In-country income | Global income | ||||
| EU Digital Levy | Paused | 3% | EU €50m | €750m | Marketplaces; advertising |
| Austria | Jan 2020 | 5% | €25m | €750m | Advertising |
| Belgium | 2027 | 3% | €5m | €750m | Advertising; Intermediation; Data Transmission |
| Czech | Proposed | 5% | CZK 100m | €750m | Advertising; digital services |
| Denmark | Jan 2024 | 2% | Streaming video | ||
| France | Jan 2019 | 3% | €25m | €750m | Digital interface; advertising; user data |
| Germany | TBC | 10% | €25m | €750m | Digital advertising |
| Greece | Jul 2019 | Nil | n/a | Tourist accomodation | |
| Hungary | Jul 2019 | 0% to Dec 2022; then 7.5% | HUF 100m | n/a | Media content; Advertising |
| Italy | Jan 2020 | 3% | Nil | €750m | Advertising; digital interfaces; user data |
| Italy | Jan 2026 | 2% | Nil | - | AgCom levy on digital & platforms |
| Latvia | Paused | 3% | €750m | Digital interface; advertising; user data | |
| Norway | Paused | Subject to progress on OECD plans | |||
| Poland | Jul 2020 | 1.5% | Streaming media and Audiovisual media service and audiovisual commercial communication | ||
| Poland 2 | Proposed | 3% | Platform, advertising and user data services | ||
| Portugal | Feb 2021 | 1.5% | Video-sharing platforms and subscription TV streaming (1%) | ||
| Portugal 2 | Proposed | 7% | Streaming video services | ||
| Slovakia | Proposed | ||||
| Slovenia | Proposed | Advertising; user data | |||
| Spain | Jan 2021 | 3% | €3m | €750m | Advertising; user data |
| Turkey | Mar 2020 | 7.5% | TRY 20m | €750m | Advertising; Content; social media |
| UK | Apr 2020 | 2% | UK £25m | £500m | Marketplaces; Social media; search engines |