First Belgian ViDA law tackles mainly OSS and e-commerce technical changes
The major 2028 platform and Single VAT Registration reforms, and 2030 digital reporting, are still to come

Belgium is moving ahead with the first stage of its implementation of the EU VAT in the Digital Age (ViDA) reforms.
The legislation, presented following parliamentary consideration in October, is a partial transposition of the ViDA Directive. It covers changes applying mainly from 1 January 2027, together with the later withdrawal of the existing call-off stock simplification.
It does not implement the whole ViDA package.
What changes from January 2027? Single VAT Registration prep
The first stage is largely technical to support the Single VAT Registration pillar, updating Belgium’s VAT rules for changes to the existing One Stop Shop (OSS), e-commerce and distance selling regimes.
The measures include changes to:
- the €10,000 threshold for intra-EU distance sales and certain digital services;
- VAT payment rules for distance sales;
- the non-Union and Union OSS schemes;
- OSS treatment of certain gas, electricity, heating and cooling supplies;
- interaction between OSS and the VAT exemption scheme for small businesses; and
- existing deemed-supplier rules for supplies facilitated through electronic interfaces.
These correspond with the EU-wide 1 January 2027 ViDA milestone, which the European Commission describes as relatively minor clarifications affecting OSS and IOSS.
Call-off stock heads for withdrawal
The legislation also starts dismantling the existing EU call-off stock simplification.
No new transfers will be possible under the regime after 30 June 2028, with the remaining transitional provisions ending by 30 June 2029.
This prepares for ViDA’s wider Single VAT Registration (SVR) reforms, including the new OSS scheme for transfers of own goods.
But most of ViDA is still to come
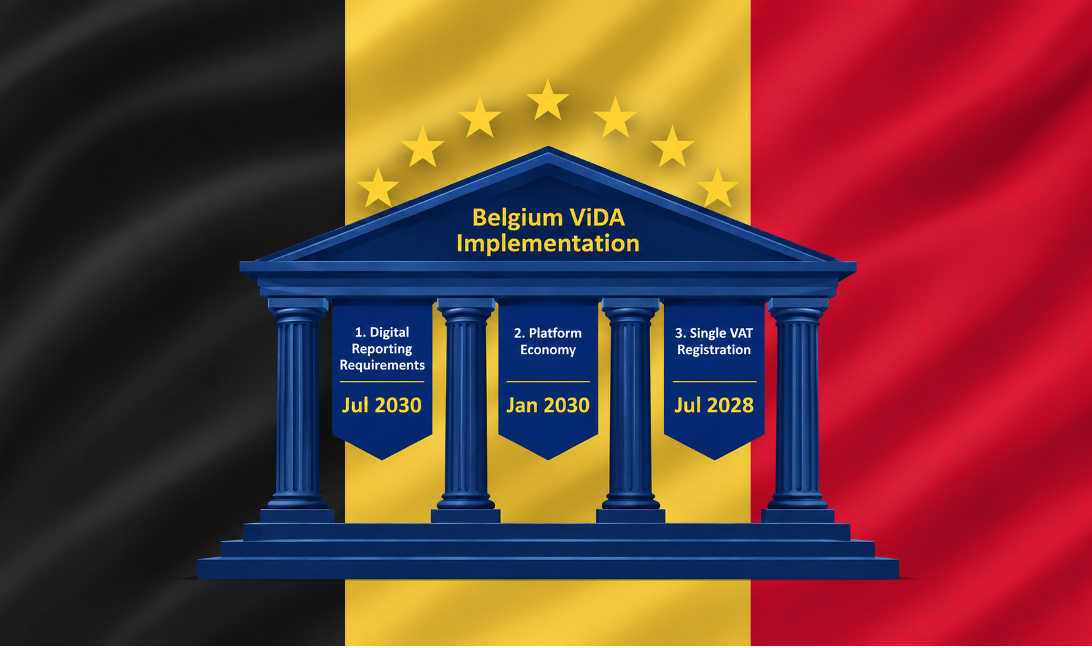
ViDA has three main pillars: Digital Reporting and e-invoicing, the Platform Economy, and Single VAT Registration.
This first Belgian law touches principally the OSS/SVR architecture and some existing platform/e-commerce provisions. It should not be confused with implementation of the three pillars in full.
The bigger changes follow later:
1 July 2028 – Single VAT Registration: wider OSS coverage, including transfer of own-goods, and mandatory reverse charge rules designed to reduce foreign VAT registrations.
1 July 2028 / 1 January 2030 – Platform Economy: new deemed-supplier VAT obligations for short-term accommodation and passenger transport platforms. Member States may defer these measures until 2030.
1 July 2030 – Digital Reporting Requirements: EU-wide transaction-level digital reporting for intra-EU B2B transactions, built around structured e-invoicing.
Further Belgian legislation will therefore be required as the remaining ViDA reforms take effect.
Belgium is already ahead on domestic digital reporting VAT
There is an important distinction with Belgium’s own domestic reforms.
Belgium’s mandatory structured B2B e-invoicing regime has already applied since 1 January 2026, independently of the 2030 ViDA cross-border DRR requirement. Belgium is also preparing domestic near-real-time transaction reporting from January 2028.
So the October legislation is not Belgium suddenly implementing ViDA in one go.
It is the first legislative instalment of a much longer transition.