

Following Jan 2026 B2B e-invoicing, draft law introducing 2028 e-reporting
18 July 2026: Federal Cabinet approves draft law mandating 5-corner e-reporting on domestic B2B transactions from 1 January 2028. This will require both supplier and their customer to separately report the transaction. E-reporting will replace the annual client listing.
13 May: debate on including from Jan 2028 non-residents in e-invoicing obligations
6 May: Federal Public Service (FPS BOSA) updated its FAQ’s on the new e-invoicing mandate, reflecting issues since the 1 January 2025 mandate launch.

2026 B2B Peppol e-Invoicing; 2028 e-Reporting to govt
Belgian Peppol-based B2B e-invoicing exchange went live on 1 January 2026. This applies only to resident businesses. This will be followed by e-reporting to the tax authorities from 1 January 2028 which precedes July 2030 EU-level e-reporting.
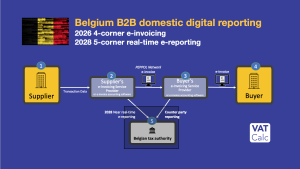
- Since 1 January 2026, Belgian-established VAT taxpayers must issue and receive structured e-invoices for domestic B2B transactions, using European standard formats and networks References: E-invoicing law.
- From January 2028, invoice data will be transmitted to the tax authority almost immediately after issuance, replacing periodic customer listings.
1. January 2026: Mandatory B2B e-invoicing
Since the start of 2026, invoices exchanged between Belgian VAT-registered businesses for transactions located in Belgium must be issued in a structured electronic format. Paper invoices and PDFs cease to be legally valid for these transactions.
The obligation applies broadly to Belgian-established taxable persons making B2B supplies of goods or services subject to Belgian VAT, including domestic reverse-charge scenarios. Credit notes fall within scope as well.
2. Which taxpayers and transactions in scope
Included
- Belgian-established VAT taxpayers engaging in domestic B2B transactions.
- Businesses must both issue and be capable of receiving compliant e-invoices.
Excluded
- B2C transactions (sales to private individuals).
- Entities making only VAT-exempt supplies under Article 44 of the Belgian VAT Code.
- Certain special regimes (e.g. flat-rate taxpayers, bankrupt entities, while those regimes exist).
- Non-established businesses holding only a Belgian VAT registration, without a Belgian fixed establishment.
Cross-border transactions (intra-EU or extra-EU) are out of scope for the 2026 mandate and continue under existing EU VAT reporting rules until the EU July 2030 Digital Reporting Requirements take effect.
3. Format and transmission: Peppol as the backbone
Belgium has anchored its approach in the European e-invoicing standard EN 16931, implemented operationally through the Peppol network.
Key characteristics:
- Invoices must be issued as structured XML files (Peppol BIS 3.0 / UBL 2.1).
- All existing VAT invoice data requirements remain, but must now be machine-readable.
- VAT rounding will be standardised at total-per-rate level to ensure automated consistency.
Peppol’s four-corner model, adopted for 2026 by Belgium, enables secure exchange between supplier and customer via certified access points. Alternative channels (such as EDI) may be used only if they fully comply with the same European semantic and syntax standards. Every in-scope business must, in any event, be Peppol-capable.
4. January 2028: near real-time e-reporting
From 1 January 2028, Belgium introduces continuous transaction reporting for domestic B2B invoices. The tax authority effectively becomes a participant in the exchange network through a five-corner Peppol model.
In practice:
- Invoice data will be forwarded to the tax administration almost immediately after issuance.
- Reporting is transaction-by-transaction, not periodic.
- The annual VAT customer listing will be abolished, as the information will already be available in real time.
Technical specifications are still being developed, but the policy intent is clear: rapid visibility of VAT data to improve controls and reduce fraud.
5. Archiving and audit readiness
Electronic invoices must be retained for 10 years, with guarantees of integrity, authenticity and readability. Digital archiving is permitted, including cloud storage and cross-border hosting, provided tax inspectors can access records promptly.
Failure to produce compliant invoices during an audit can result in denied VAT deductions and financial penalties.
6. Penalties and enforcement
Belgium combines traditional VAT sanctions with new, technology-specific penalties:
- Invalid invoicing can lead to denial of VAT deduction for customers and proportional fines linked to the VAT amount.
- Separate fixed administrative fines apply for failing to implement compliant e-invoicing systems, escalating with repeated offences:
- €1,500 for first offence.
- €3,000 for second offence.
- €5,000 for third offence within 3 months.
- The Q1 2026 tolerance period temporarily shields businesses acting in good faith, but enforcement tightens rapidly thereafter.
Once e-reporting begins, automated cross-checks will significantly increase detection of non-compliance.
7. Incentives for businesses on e-invoicing investment
- From 1 Jan 2025:
- 20% investment deduction for digital investments.
- 120% fee deduction for small businesses/independents using subscription billing software (2024–2027 taxable periods).
8. Belgian domestic e-invoicing aligns with ViDA July 2035 e-invoicing
Belgium is looking to synchronise with the EU VAT in the Digital Age plans for an EU standard on eInvoicing (EN 16931) system across the EU to ensure interpretability. Under the Digital Reporting Requirement pillar, there is a planned mandatory structured e-invoicing requirement in the EU for intra-community supplies from 2030 or later.


