Cabinet Regulation sets out obligations for 2028 B2B e-invoicing mandate
-
Latvia has issued detailed procedural regulations governing structured e-invoicing and data submission to the State Revenue Service (SRS), ahead of its planned 2028 mandate.
-
The framework adopts EU standards (UBL 2.1 and PEPPOL BIS Billing 3.0) and allows multiple transmission models, including APIs and accredited service providers.

Businesses will be required to submit e-invoice data to the SRS within five working days of issuance, embedding near-real-time reporting into invoice workflows.
Cabinet Regulation sets broad scope and rules for e-invoicing
On 9 December 2025, Latvia’s Cabinet of Ministers adopted Regulations No. 749, setting out the operational framework for the circulation of structured electronic invoices and the submission of e-invoice data to the State Revenue Service. Issued under Section 11(15) of the Accounting Law, the regulations provide the clearest indication yet of how Latvia’s planned 2028 e-invoicing mandate will function in practice.
- Mar 2026 1st phase e-invoicing:
- Update existing free e-invoicing form
- Voluntary issuance of B2B e-invoices via e-mail (similar to current German e-invoicing phase)
- Jan 2028 2nd phase e-reporting:
- automated e-reporting of e-invoices to the Latvian State Revenue Service
The rules apply to all entities falling within the scope of Latvia’s Accounting Law. They govern both:
-
the exchange of structured electronic invoices between businesses, and
-
the submission of structured invoice data to the State Revenue Service.
E-invoices are defined as XML-based electronic documents conforming to EU-specified structured formats, transmitted via approved electronic delivery channels.
Approved delivery channels
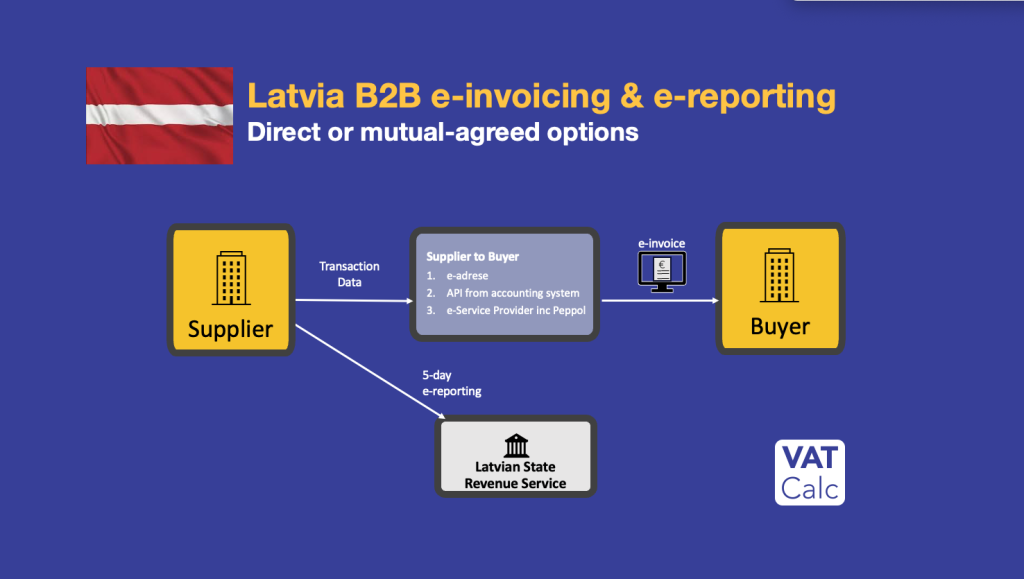
Latvia has opted for a decentralised exchange model, allowing businesses flexibility in how e-invoices are transmitted. Companies may use one or more of the following channels:
-
the Official Electronic Address system (where activated);
-
a service provider or operator offering e-invoicing and reporting services; or
-
other electronic channels, including system-to-system integrations or secure email-based solutions.
Trading partners must agree on the delivery channel(s) used, placing greater emphasis on interoperability and contractual alignment between counterparties.
Central submission to the tax authority
To support decentralised exchange, the State Revenue Service will establish and operate a dedicated e-invoice submission solution. Through this platform, the SRS will receive and store structured e-invoices (excluding attachments) submitted by taxpayers.
Critically, the regulations mandate that invoice data submitted to the SRS must comply with:
-
UBL 2.1, and
-
PEPPOL BIS Billing 3.0, including the relevant Core Invoice Usage Specification (CIUS).
This firmly anchors Latvia’s model within the broader European e-invoicing ecosystem and supports cross-border consistency.
Submission methods and reporting logic
Issuing companies must submit e-invoice data to the SRS using one or more of the following methods:
-
the Official Electronic Address;
-
a service provider or operator API integrated with SRS systems; or
-
the SRS Electronic Declaration System API or file upload functionality.
Where the Official Electronic Address is used, invoice reporting to the SRS is automated, provided that both the company and its service provider operate up-to-date, compatible software.
Importantly, where alternative delivery channels are used between trading partners, separate submission to the SRS remains mandatory, reinforcing the distinction between commercial exchange and tax reporting.
Timing and resilience requirements
E-invoices must be submitted to the SRS no later than five working days after issuance. This introduces a defined reporting window that effectively moves Latvia closer to continuous transaction controls, even without a real-time clearance model.
The regulations also address system failures. Where submission is prevented by technical malfunctions, companies or service providers are required to notify the SRS and complete submission once systems are restored, ensuring continuity of reporting obligations.
Latvia joins European dash for transaction-based VAT reporting
Latvia will join Italy’s SdI pre-clearance model, which Belgium, Bulgaria and France are rolling out in the forth coming 24 months. Whilst others have opted for post-issuance live invoice reporting, including Hungary, some like Spain e-invoicing proposal show a switch to the model used across South America and Asia.
EU VAT in the Digital Age reforms include a channel for harmonised Digital Reporting Requirements (DRR) and Continuous Transaction Controls (CTC) by EU states. This grew from the 2020 Tax Package proposals for a fairer and more efficient EU tax regime.
VAT Calc’s VAT Calculator tax engine can provide live global VAT or GST determination for your e-invoicing or real-time reporting obligations.
PEPPOL – EU standard for einvoicing going global
(Pan-European Public Procurement Online) is a set of specifications maintained by the OpenPEPPOL non-profit organisation with the aim of standardizing cross-border, electronically supported procurement procedures. PEPPOL is managed by the OpenPEPPOL Association. It features, among other things, electronic invoicing. In addition to specifications PEPPOL consists of a delivery network. It started off as a development project with the same name under the European union Competitiveness and Innovation Programme from May 2008 to August 2012.