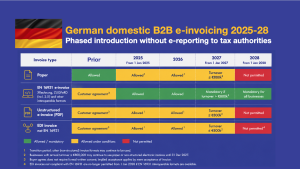
2025-28 B2B e-invoicing phased introduction
Federal Ministry of Finance updates requirements; indicates e-reporting next
2 Sept 2026: German Ministry of Finance BMF Bundesministerium der Finanzen) clarifies rules ahead of the end-2026 transition: mandatory VAT data to be structured, corrections electronic, validation broader, and non-compliance may brings penalty risks
18 July: BMF launches Action Plan with Germany e-reporting via centralised database mapped out. No implementation dates yet
23 Mar: the BMF has updated the Frequently asked Questions

B2B e-invoicing: 2025-28 mandate, BMF FAQs and invoice formats
Germany has started its phased introduction of mandatory B2B e-invoicing, with all businesses now expected to be able to receive structured electronic invoices and issuing obligations following from 2027.
The reform is part of Germany’s Growth Opportunities Act and is designed to prepare the country for a future domestic digital reporting regime. It also aligns Germany more closely with the EU’s wider VAT in the Digital Age reforms.
Germany e-invoicing timeline
Germany’s B2B e-invoicing mandate is being introduced in phases:
- 1 Jan 2025 – all German businesses must be able to receive structured B2B e-invoices
- 1 Jan 2027 – businesses with annual turnover above €800,000 must issue e-invoices
- 1 Jan 2028 – all German businesses must issue e-invoices
The Federal Ministry of Finance has now issued detailed guidance through its BMF letters of 15 October 2024 and 15 October 2025, supported by updated FAQs. (Bundesministerium der Finanzen)
What counts as an e-invoice in Germany?
Since 2025, Germany distinguishes between:
Electronic invoices, meaning invoices issued, transmitted and received in a structured electronic format that allows automated processing; and
Other invoices, including paper invoices, standard PDFs and other unstructured formats.
A simple PDF sent by email is therefore not an e-invoice for the purposes of the German B2B mandate.
The permitted structured formats must comply with the European e-invoicing standard EN 16931. This includes formats such as XRechnung and ZUGFeRD, provided they contain the required structured invoice data. (Bundesministerium der Finanzen)
XRechnung, ZUGFeRD and hybrid invoices
Germany allows both fully structured XML invoices and hybrid formats.
XRechnung is a pure XML format widely used in German public procurement. ZUGFeRD combines a human-readable PDF with embedded XML invoice data. However, the structured XML component is the legally relevant invoice data for VAT purposes.
ZUGFeRD 2.5 was released in May 2026, including updates such as support for gross invoice scenarios and alignment with the latest EN 16931 code lists. Businesses using ZUGFeRD should confirm that their software supports the latest compliant version.
Attachments and supporting documents
The BMF has clarified that the mandatory invoice information must be included in the structured data. Businesses cannot simply attach a PDF and treat that as the compliant invoice.
However, attachments can still support the invoice. For example, detailed timesheets, construction schedules or other supporting breakdowns may be included where the structured invoice data clearly references them. This is important for sectors with complex invoice backing documentation. (Bundesministerium der Finanzen)
Cash purchases and low-value invoices
The German rules may also affect transactions that businesses have not traditionally treated as e-invoicing issues.
The BMF FAQs confirm that B2B cash purchases above €250 may require an e-invoice once the transitional rules have expired. This means German e-invoicing is not just an ERP-to-ERP accounts payable issue. It may also affect expense processes, procurement cards, local purchasing and employee reimbursement controls. (Bundesministerium der Finanzen)
German Electronic Business Address: GEBA
Germany is also developing the German Electronic Business Address, or GEBA. This is based on the German business identification number, the W-IdNr., and is designed to provide a standard electronic address for business communications.
GEBA can also be used as a Peppol Participant ID, supporting Germany’s future e-invoicing interoperability. This is not yet the main legal obligation, but it is a practical development businesses should monitor when designing their German invoice routing architecture. (edicomgroup.com)
VATCalc e-invoicing and VAT reconciliation
VATCalc helps businesses manage German e-invoicing as part of end-to-end VAT compliance.
Its platform supports VAT determination, invoice validation, e-invoicing and reconciliation between transactional data, structured invoice data and VAT return reporting. This helps businesses identify differences before filing and maintain a clear audit trail across invoice issue, receipt, VAT treatment and reporting.
As Germany moves from e-invoicing to wider digital VAT controls, businesses should focus on integrated compliance rather than isolated invoice transmission.
Council of EU approves mandatory German e-invoicing
The request by the European Commission on behalf of Germany to introduce mandatory B2B domestic VAT e-invoicing was approved by the Council of the European Union on 25 July. This allows Germany to impose real-time e-invoicing
The request was backed by the EU Commission in June (see below) to authorise Germany to derogate from the EU VAT Directive and its requirement for paper-based invoices. Germany will be permitted to impose e-invoices until the end of 2027 when there will be a further review.
Read more about German VAT in our national guide.
Germany B2G e-invoices
As per the requirements of the EU VAT Directive on e-invoicing, in April 2020, Germany mandated the acceptance of electronic invoices for Federal governmental transactions with the commercial sector, B2G.The format varies by state (Bundesland) as they adopt the legislation in their local laws. The states have the option of their own format (which should be PEPPOL compliant) or the recommended by Core Invoice User Specification (CIUS).