Poland has approved the first stage of its ViDA, covering e-commerce and OSS changes Jan 2027 and the later withdrawal of call-off stock
Major Single VAT Registration, platform and digital reporting reporting to follow

Poland is progressing legislation to implement the first stage of the EU’s VAT in the Digital Age (ViDA) reforms.
Government Bill No. 3074 was passed by the Sejm on 8 October 2026. The Senate subsequently proposed an amendment, which returned to the Sejm for consideration.
The legislation specifically implements Articles 2 and 4 of Directive (EU) 2025/516. It therefore does not transpose the complete ViDA package.
Single VAT Registration changes from January 2027
The first Polish measures, under the Single VAT Registration (SVR) pillar, focus primarily on improving the VAT e-commerce rules introduced in July 2021 and extending the circumstances in which businesses can use the One Stop Shop (OSS) rather than registering for VAT separately in different Member States.
Changes include clarification of the deemed-supplier rules applying to online marketplaces and other electronic interfaces.
The €10,000 threshold for intra-EU distance sales is also refined so that qualifying sales are determined by reference to goods dispatched from the Member State in which the supplier is established.
OSS is extended to certain cross-border supplies of gas, electricity, heating and cooling, reducing the need for suppliers to obtain additional local VAT registrations.
Poland prepares to withdraw call-off stock
The legislation also implements ViDA’s later withdrawal of the existing call-off stock simplification.
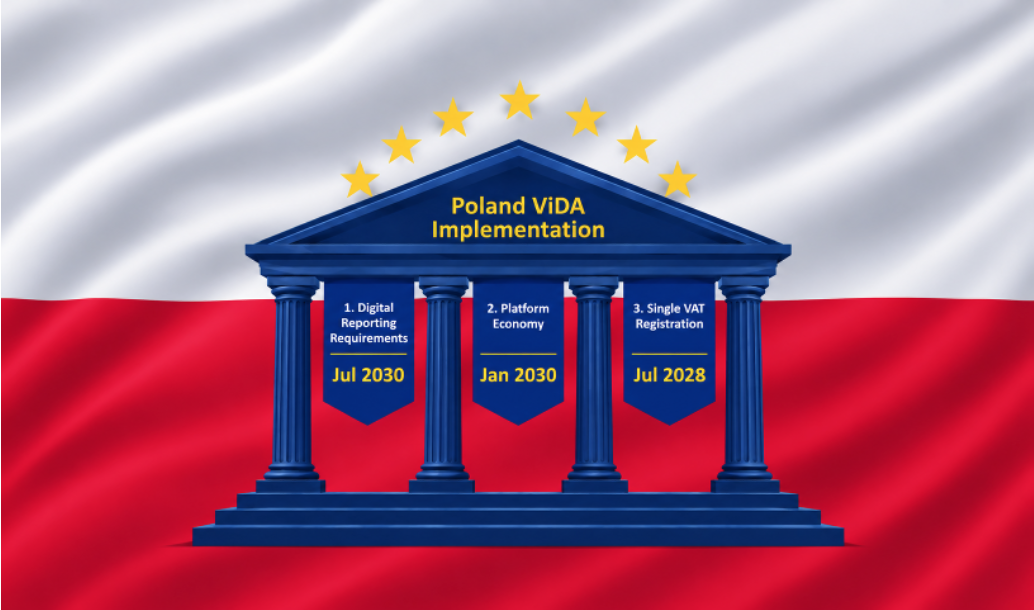
New movements under the regime will cease from 1 July 2028. Existing arrangements may continue under transitional rules until 30 June 2029, after which the current simplification disappears.
This prepares for another important ViDA reform: the new Transfer of Own Goods (TOOG) OSS scheme from July 2028.
TOOG will allow businesses to report qualifying movements of their own inventory between EU Member States through OSS, reducing the foreign VAT registrations currently triggered by many stock movements.
But the major 2028 ViDA reforms are still to come
The present bill implements the initial 2027 e-commerce measures and Article 4 call-off stock changes.
The much larger Single VAT Registration reforms from July 2028 will require additional measures. These include the TOOG scheme and harmonisation of mandatory reverse charge treatment intended to reduce VAT registrations for non-established businesses.
The Platform Economy reforms also apply from this later stage, introducing deemed-supplier obligations for qualifying short-term accommodation and passenger transport supplied through digital platforms.
KSeF is separate from ViDA’s 2030 digital reporting
Poland is already introducing its domestic KSeF mandatory e-invoicing regime. That is a national VAT digitisation programme and should not be confused with Poland’s implementation of ViDA’s EU-wide Digital Reporting Requirements.
ViDA’s Digital Reporting Requirements (DRR) apply from July 2030 to intra-EU B2B transactions and will replace the existing recapitulative statement system with transaction-level digital reporting based on structured electronic invoices.
See more in our Poland VAT Country guide.
EU member states ViDA implementation tracker
| Country (click for details) | Status | Latest | |
| 1 | Austria | ⚪ Awaiting legislation | - |
| 2 | Belgium | 🟠 Bill presented | OSS, distance sales, electronic interfaces and related changes |
| 3 | Bulgaria | ⚪ Awaiting legislation | - |
| 4 | Croatia | 🟡 Draft / consultation | Draft partial transposition for January 2027 |
| 5 | Cyprus | ⚪ Awaiting legislation | - |
| 6 | Czech Republic | 🟠 Parliamentary legislation | OSS changes from January 2027 |
| 7 | Denmark | ⚪ Legislative timetable set | - |
| 8 | Estonia | 🟠 Bill before Parliament | Bill 992 SE: OSS and related changes from January 2027 |
| 9 | Finland | ⚪ Awaiting legislation | National implementation needs confirmation |
| 10 | France | ⚪ Awaiting legislation | ViDA measures notified, but first-stage position needs separating from domestic e-invoicing reforms |
| 11 | Germany | ⚪ Awaiting / monitor | - |
| 12 | Greece | ⚪ Awaiting legislation | - |
| 13 | Hungary | ⚪ Awaiting legislation | - |
| 14 | Ireland | ⚪ Awaiting legislation | - |
| 15 | Italy | 🟡 Draft legislation | Draft legislative decree – parliamentary scrutiny completed |
| 16 | Latvia | ⚪ Awaiting legislation | - |
| 17 | Lithuania | 🟢 Adopted | Law XV-1036 implements initial ViDA changes from January 2027 |
| 18 | Luxembourg | 🟠 Bill before Parliament | Bill 8812 transposes Article 2 from January 2027 |
| 19 | Malta | 🟢 Adopted | Act III of 2026 implements Article 2 from January 2027 |
| 20 | Netherlands | 🟢 Adopted | Implementation Act published October 2026; January 2027 commencement |
| 21 | Poland | 🟠 Parliamentary legislation | Bill 3074 passed Sejm; January 2027 provisions |
| 22 | Portugal | ⚪ Awaiting legislation | - |
| 23 | Romania | ⚪ Awaiting legislation | - |
| 24 | Slovakia | 🟡 Draft legislation | ViDA transposition combined with January 2027 domestic e-invoicing reforms |
| 25 | Slovenia | ⚪ Awaiting legislation | - |
| 26 | Spain | 🟠 Government legislation | Partial ViDA transposition underway in Parliament |
| 27 | Sweden | ⚪ Awaiting legislation | - |