2026 1st and 2nd KSeF B2B e-invoicing postpones penalties till 2028
16 September 2026: Ministry of Finance has extend the soft-landing, no penalty phase of KSeF by a further 12 months; no fines before 1 Jan 2028
9 June: Consultations on updates to business event models, invoice process management and enhancements.
1 April: Poland launched February and April 2026 waves of mandatory KSeF B2B e-invoicing, including issuing a new Frequently Asked Questions online help and confirming no penalties during 2027.
The third wave, of micro-businesses, goes live on 1st January 2027.


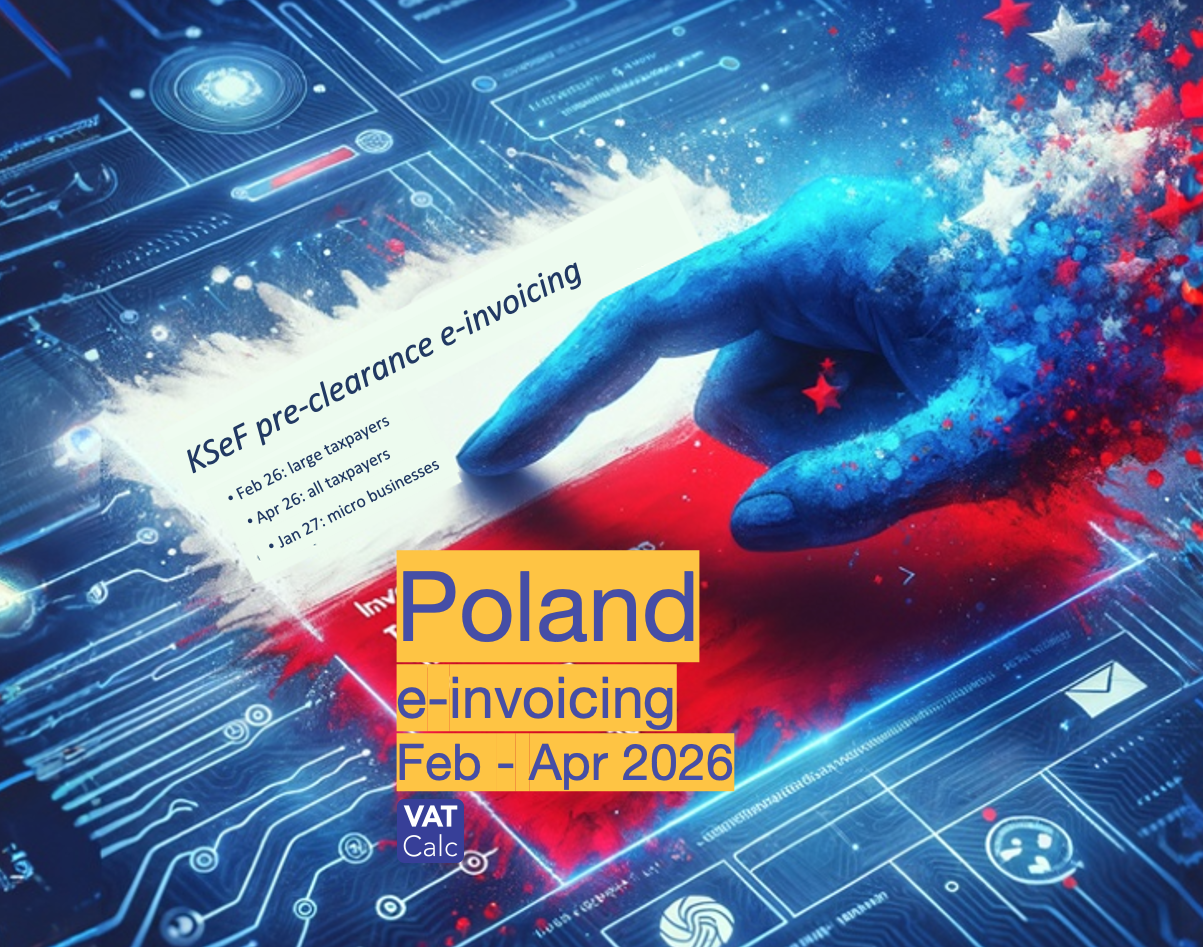
KSeF e-invoicing launch timetable is now:
- LAUNCH 1st Feb: large taxpayers, over PLN 200m (2024) pa turnover; and
- LAUNCH 1st Apr: other taxpayers.
- 1st Aug: bank transfer ID references must be added for KSeF
- LAUNCH: Jan 2027
- micro businesses – invoices below PLN450 and less than PLN 10,000 sales per month;
- penalty regime stars for Feb 2026 candidates
- Reporting of e-invoices on cash registers;
- obligation to add KSeF numbers in transfers of invoices between businesses
- ‘Offline24‘ mode now permanent, allowing invoices to be reported following day, including split payments. Any taxpayer issuing in Offline24 will need special approval, available 1 November 2025.
- QR Code now in single format to be added to any paper/PDF produced version of e-invoice;
- Option for B2C e-invoicing via KSeF
Transactions subject or excluded from KSeF pre-clearance
Poland’s e-invoicing regime applies to most domestic VAT-relevant supplies by resident taxpayers, but the obligation is not universal.
Transactions Requiring KSeF
-
Domestic B2B supplies
Invoices for transactions between businesses that are both VAT-registered in Poland must be issued through KSeF. This forms the core of the mandate.
-
Supplies to public bodies (B2G)
Sales to Polish public sector organisations are also covered and must follow the same structured e-invoicing process.
-
Outbound cross-border transactions
Polish VAT-registered sellers are required to submit invoices relating to exports and intra-EU supplies to KSeF, even where VAT is charged at 0%. Although the invoice is reported to the tax authority via KSeF, the foreign customer does not access the system. Instead, the seller must provide the buyer with a copy (for example, a PDF) containing the KSeF reference and verification code.
Transactions Outside Mandatory KSeF
-
Domestic B2C supplies
Invoices issued to private individuals are not subject to mandatory clearance, as consumers generally have no access to KSeF. Traditional invoicing or fiscal receipts continue to apply, although voluntary use of KSeF remains possible.
-
Inbound cross-border invoices
Invoices issued by non-Polish suppliers that are not VAT-registered in Poland are exchanged outside KSeF and are handled through standard VAT reporting by the Polish recipient.
-
Specific exemptions and transitional carve-outs
Temporary exclusions apply to certain small taxpayers (subject to turnover thresholds), limited cases of digital exclusion, selected self-billing arrangements, and transactions reported through OSS or IOSS schemes. Documents such as pro forma invoices and tickets treated as invoices are also outside scope.
Taxpayers Subject to the Obligation
Responsibility for issuing invoices via KSeF rests primarily with suppliers registered for Polish VAT.
-
Entities established in Poland
Businesses with a registered seat in Poland fall squarely within scope, regardless of whether they are VAT-taxable or VAT-exempt. Both categories are required to issue structured electronic invoices through KSeF.
-
Foreign entities with a Polish fixed establishment
Non-Polish companies that operate in Poland through a fixed establishment involved in taxable supplies are required to comply in the same way as domestic businesses.
-
Foreign VAT registrations without physical presence
Where a business is registered for Polish VAT but lacks personnel or infrastructure in Poland, mandatory use of KSeF may not apply, reflecting a policy choice to limit administrative burden.
-
Obligations for buyers
Polish VAT-registered customers must be technically prepared to receive invoices via KSeF. Acceptance of KSeF-issued invoices is mandatory under Polish law.
Invoice Structure and Data Standards
Invoices submitted to KSeF must follow a strictly defined electronic format.
-
FA(3) XML schema
Poland mandates the FA(3) structured XML format, representing the latest version of its national e-invoice schema. The design aligns with European e-invoicing standards, including EN 16931 and Peppol BIS conventions.
-
Required invoice data
All statutory invoice elements must be populated in structured fields, including supplier and customer identifiers, dates, invoice numbering, itemised transaction details, VAT rates and amounts, totals, currency, and any legally required remarks such as reverse-charge indicators.
-
System-generated identifiers
Once validated, KSeF assigns each invoice a unique reference number and enables the generation of a QR code. These identifiers allow third parties to confirm the invoice’s authenticity against the central system.
-
No supplier e-signature requirement
Suppliers are not required to apply a qualified electronic signature. Legal integrity and authenticity are ensured through submission to KSeF, which timestamps and seals the invoice.
Submission, clearance, and customer delivery
-
System access
Businesses can connect to KSeF via APIs (commonly used by ERP and billing systems) or through free government-provided interfaces, including a web portal, mobile tools, and a simplified solution for micro-enterprises. Secure authentication is mandatory.
-
Clearance process
Invoices are validated automatically upon submission. Only invoices that pass validation are registered, timestamped, and legally recognised as issued. Rejected invoices are treated as never issued.
-
Invoice receipt
For Polish recipients, legal delivery occurs when the invoice is made available in KSeF. Foreign recipients receive invoices outside the system, accompanied by the KSeF identifier or QR code.
-
Timing requirements
Invoices are expected to be submitted to KSeF at the time of issuance or very close to the taxable event.
-
Offline contingency
Where technical issues prevent real-time submission, invoices may be issued offline but must be uploaded to KSeF no later than the following business day. Equivalent rules apply during KSeF outages.
KSeF penalties
Poland has adopted a phased enforcement approach.
-
Transitional relief
No monetary penalties apply for KSeF breaches during 2026, allowing businesses a full adaptation period:
-
up to the full VAT amount shown on the invoice, or
-
where no VAT is charged, up to approximately 18.7% of the gross invoice value.
Sanctions from 1 January 2027
Administrative fines may be imposed where mandatory KSeF invoicing is not respected.
-
-
Additional consequences
Failure to comply with offline upload rules may also trigger penalties. Non-compliant invoices risk being rejected for VAT deduction purposes and may be refused by trading partners.
Retention and archiving requirements
-
Centralised storage
All invoices submitted via KSeF are retained by the tax authority for a period of ten years, exceeding Poland’s VAT limitation period.
-
Reduced taxpayer burden
Businesses are not required to maintain separate tax archives for KSeF invoices, as the central system constitutes the official record.
-
Access rights
Taxpayers can retrieve their invoices from KSeF throughout the retention period.
-
Practical considerations
Although not legally required, maintaining internal copies remains advisable for operational, analytical, and continuity purposes.
The European Commission granted Polish e-invoicing derogation from the VAT Directive in March 2022.
Check VAT Calc’s global live VAT invoice transaction and e-invoice reporting tracker to see where else real-time submissions of invoices is being implemented.
Read more in our Polish VAT guide.
EU harmonised live transaction VAT reporting proposals
EU VAT in the Digital Age reforms include a channel for harmonised Digital Reporting Requirements (DRR) and Continuous Transaction Controls (CTC) by EU states. This grew from the 2020 Tax Action Plan proposals for a fairer and more efficient EU tax regime.
For invoice VAT calculations, you can check the right VAT calculations on individual or batch transactions with our Advisor and Auditor tool.