Croatia legislation implementing the first stages of the EU’s VAT in the Digital Age (ViDA) reforms
Extensions to OSS and IOSS, online marketplace VAT liabilities and preparations for Single VAT Registration in July 2028

The Croatian Parliament approved the proposed amendments to its VAT Act for VAT in the Digital Age EU reforms at first reading on 25 September 2026. The final Bill (P.Z.E. No. 342) was submitted for second reading on 6 November, with most changes scheduled to take effect on 1 January 2027.
The legislation implements elements of Council Directive (EU) 2025/516, adopted in March 2025.
Croatia’s proposed 2027 ViDA VAT changes
The principal amendments include:
- OSS expansion: Extending the non-EU OSS scheme to all B2C services supplied within the EU by non-EU established businesses.
- Online marketplaces: Broadening deemed supplier rules to cover additional supplies facilitated by electronic platforms to customers not liable for VAT on intra-EU acquisitions.
- €10,000 distance selling threshold: Clarifying that the threshold applies to qualifying intra-EU distance sales dispatched from the supplier’s Member State of establishment. Businesses may opt for destination taxation, binding them for two calendar years.
- IOSS restrictions: Excluding businesses using the special EU SME VAT exemption scheme from simultaneously applying IOSS.
- VAT refunds: Clarifying refund procedures for businesses registered under OSS and IOSS.
- Energy supplies: Maintaining transitional distance-selling treatment for certain electricity, heating and cooling supplies until 30 June 2028.
Preparing for Single VAT Registration in July 2028
The amendments also prepare Croatia for the next phase of ViDA’s Single VAT Registration reforms, commencing 1 July 2028.
These include introducing an OSS mechanism for reporting qualifying intra-EU transfers of businesses’ own goods, reducing the need for multiple national VAT registrations.
Existing arrangements for transfers of own goods initiated before 1 July 2028 would remain subject to transitional provisions until 30 June 2029.
The proposed changes represent Croatia’s first legislative steps towards the wider ViDA reforms:
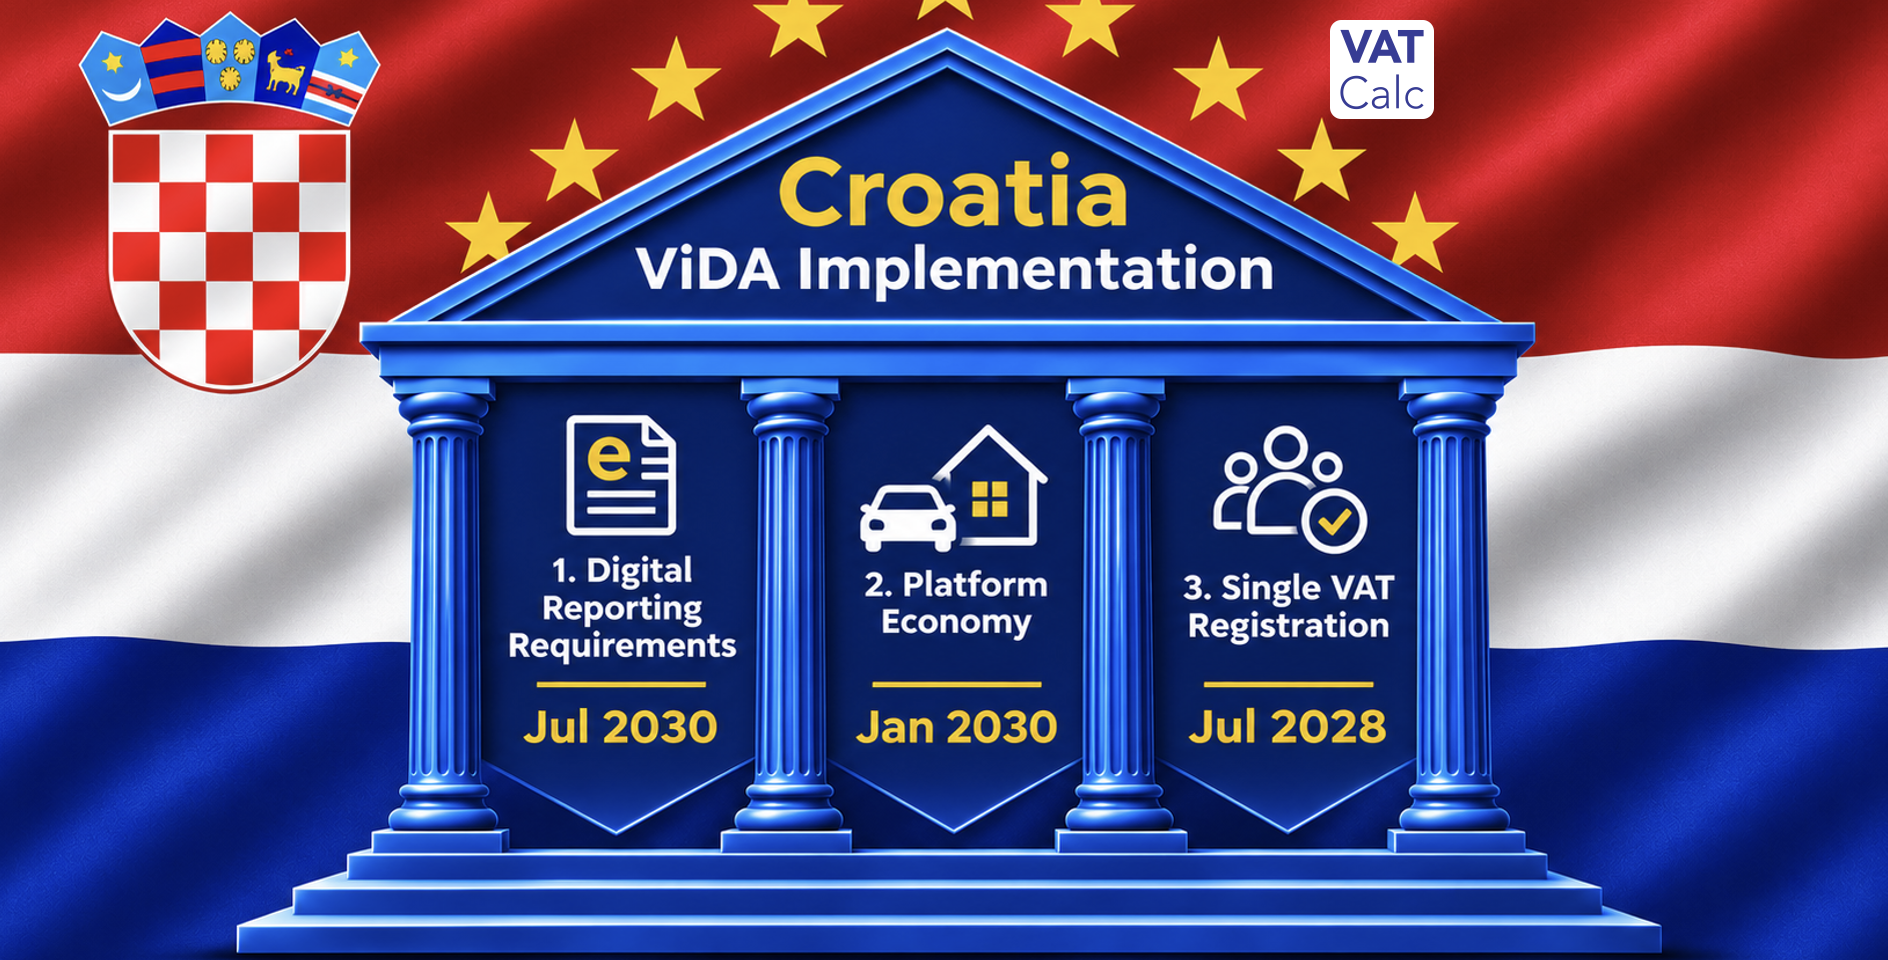
- Jul 2028 – Major Single VAT Registration reforms, including the Transfer of Own Goods OSS, withdrawal of the call-off stock simplification and mandatory reverse charge, plus the
- Jul 2028 – Jan 2030 – Platform Economy, deemed supplier gig & sharing
- 1 Jul 2030 – Cross-border e-invoicing Digital Reporting Requirements (completing 2035)
VATCalc ViDA compliance
VATCalc tracks the national implementation of ViDA legislation across all 27 EU Member States, including changes to OSS, IOSS, VAT determination and reporting obligations.
Its single legislative tax engine and VAT reporting platform support businesses adapting to the evolving requirements of EU VAT compliance.
Legislative status and sources
The important distinction is that Croatia has not yet enacted these amendments, based on the latest parliamentary records I could verify.
- 25 September 2026: Parliament approved the Bill at first reading.
- 6 November 2026: Final Bill submitted for second reading.
- 11 November 2026: Parliamentary Finance and Budget Committee scheduled its consideration of the final Bill.
EU member states ViDA implementation tracker
| Country (click for details) | Status | Latest | |
| 1 | Austria | 🟠 Draft legislation | Public consultation underway |
| 2 | Belgium | 🟠 Bill approved by Parliament | OSS, distance sales, electronic interfaces and related changes |
| 3 | Bulgaria | ⚪ Awaiting legislation | - |
| 4 | Croatia | 🟠 Bill being considered by Parliament | Draft partial transposition for January 2027 |
| 5 | Cyprus | ⚪ Awaiting legislation | - |
| 6 | Czechia | 🟠 Bill in Parliament | OSS changes from January 2027 |
| 7 | Denmark | ⚪ Legislative timetable set | - |
| 8 | Estonia | 🟠 Bill before Parliament | Bill 992 SE: OSS and related changes from January 2027 |
| 9 | Finland | 🟢 Adopted | |
| 10 | France | ⚪ Awaiting legislation | ViDA measures notified, but first-stage position needs separating from domestic e-invoicing reforms |
| 11 | Germany | 🟠 Bill before Parliament | - |
| 12 | Greece | ⚪ Awaiting legislation | - |
| 13 | Hungary | 🟠 Bill before Parliament | Initial 2027 changes only |
| 14 | Ireland | ⚪ Awaiting legislation | - |
| 15 | Italy | 🟠 Draft legislation | Draft legislative decree – parliamentary scrutiny completed |
| 16 | Latvia | 🟠 Bill before Parliament | Initial 2027 changes only |
| 17 | Lithuania | 🟢 Adopted | Law XV-1036 implements initial ViDA changes from January 2027 |
| 18 | Luxembourg | 🟠 Bill before Parliament | Bill 8812 transposes Article 2 from January 2027 |
| 19 | Malta | 🟢 Adopted | Act III of 2026 implements Article 2 from January 2027 |
| 20 | Netherlands | 🟢 Adopted | Implementation Act published October 2026; January 2027 commencement |
| 21 | Poland | 🟠 Parliamentary legislation | Bill 3074 passed Sejm; January 2027 provisions |
| 22 | Portugal | ⚪ Awaiting legislation | - |
| 23 | Romania | ⚪ Awaiting legislation | - |
| 24 | Slovakia | 🟠 Draft legislation | ViDA transposition combined with January 2027 domestic e-invoicing reforms |
| 25 | Slovenia | 🟠 Draft legislation | Partially transpose ViDA changes applying from 1 January 2027 |
| 26 | Spain | 🟠 Government legislation | Partial ViDA transposition underway in Parliament |
| 27 | Sweden | 🟠 Bill in Parliament | 2027 reforms in Parliament |