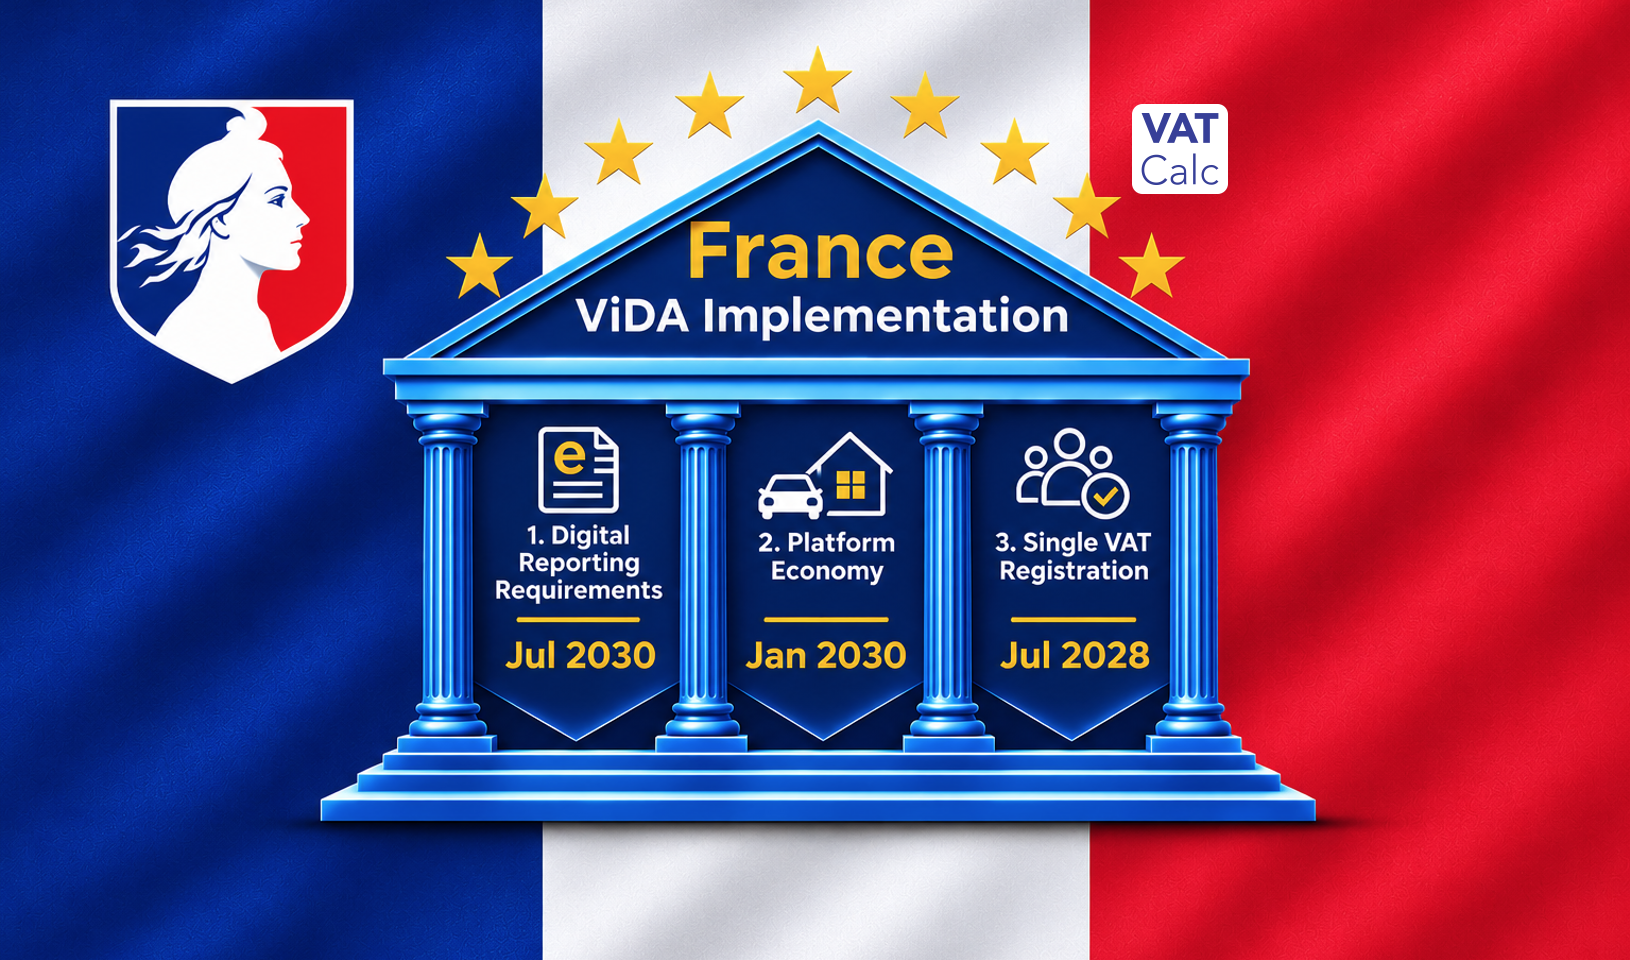
France incorporates elements of the EU VAT in the Digital Age (ViDA) reforms into national legislation, including changes for July 2028
However, the implementation of the first January 2027 OSS and IOSS amendments unclear

Unlike several EU Member States publishing dedicated ViDA implementation bills, France has incorporated reforms into its extensive VAT recodification programme.
Ordonnance No. 2025-1247 of 17 December 2025, subsequently amended in July 2026, transfers French VAT legislation from the Code général des impôts (CGI) into the Code des impositions sur les biens et services (CIBS) from 1 January 2027.
The legislation also makes substantive amendments to French VAT rules to accommodate EU reforms, including ViDA.
What has France implemented for July 2028?
Article 19 of the December 2025 ordinance introduces changes effective from 1 July 2028, including:
- Call-off stock: Removal of the existing EU call-off stock simplification, subject to transitional arrangements running until June 2029.
- Cross-border VAT arrangements: Amendments to provisions governing intra-EU transactions and related VAT treatment.
- E-commerce: Changes to provisions governing distance sales and imported goods, alongside wider EU reforms.
- VAT registration and special schemes: Amendments to provisions relevant to cross-border VAT compliance.
These changes coincide with ViDA’s major Single VAT Registration reforms, which extend OSS coverage and introduce new rules intended to reduce the need for multiple national VAT registrations.
French tax authority guidance published in October 2026 confirms that the recodification incorporates mandatory EU VAT amendments without introducing additional national options.
But where are the January 2027 changes?
The first ViDA amendments take effect on 1 January 2027, introducing adjustments and clarifications to the EU’s One Stop Shop (OSS) and Import One Stop Shop (IOSS) schemes.
Member States must adopt the necessary national measures by 31 December 2026.
While France’s legislation expressly references the ViDA Directive, a distinct transposition of these initial January 2027 amendments has not yet been clearly identified.
This does not necessarily indicate non-compliance. The relevant provisions may already be accommodated within existing French legislation or the recodified VAT rules.
Further implementation to follow
France’s tax authority has confirmed that the VAT recodification initially covers legislative provisions, with regulatory provisions to be transferred subsequently.
The wider ViDA programme will also require further changes, notably the EU’s mandatory intra-Community B2B e-invoicing and digital reporting requirements from July 2030.
France’s domestic e-invoicing and e-reporting mandate remains a separate reform.
France’s ViDA implementation is therefore already underway, particularly for July 2028. The outstanding question is how it has addressed the first January 2027 requirements.
EU member states ViDA implementation tracker
| Country (click for details) | Status | Latest | |
| 1 | Austria | 🟠 Draft legislation | Public consultation underway |
| 2 | Belgium | 🟠 Bill approved by Parliament | OSS, distance sales, electronic interfaces and related changes |
| 3 | Bulgaria | ⚪ Awaiting legislation | - |
| 4 | Croatia | 🟠 Bill being considered by Parliament | Draft partial transposition for January 2027 |
| 5 | Cyprus | ⚪ Awaiting legislation | - |
| 6 | Czechia | 🟠 Bill in Parliament | OSS changes from January 2027 |
| 7 | Denmark | ⚪ Legislative timetable set | - |
| 8 | Estonia | 🟠 Bill before Parliament | Bill 992 SE: OSS and related changes from January 2027 |
| 9 | Finland | 🟢 Adopted | |
| 10 | France | ⚪ Awaiting legislation | ViDA measures notified, but first-stage position needs separating from domestic e-invoicing reforms |
| 11 | Germany | 🟠 Bill before Parliament | - |
| 12 | Greece | ⚪ Awaiting legislation | - |
| 13 | Hungary | 🟠 Bill before Parliament | Initial 2027 changes only |
| 14 | Ireland | ⚪ Awaiting legislation | - |
| 15 | Italy | 🟠 Draft legislation | Draft legislative decree – parliamentary scrutiny completed |
| 16 | Latvia | 🟠 Bill before Parliament | Initial 2027 changes only |
| 17 | Lithuania | 🟢 Adopted | Law XV-1036 implements initial ViDA changes from January 2027 |
| 18 | Luxembourg | 🟠 Bill before Parliament | Bill 8812 transposes Article 2 from January 2027 |
| 19 | Malta | 🟢 Adopted | Act III of 2026 implements Article 2 from January 2027 |
| 20 | Netherlands | 🟢 Adopted | Implementation Act published October 2026; January 2027 commencement |
| 21 | Poland | 🟠 Parliamentary legislation | Bill 3074 passed Sejm; January 2027 provisions |
| 22 | Portugal | ⚪ Awaiting legislation | - |
| 23 | Romania | ⚪ Awaiting legislation | - |
| 24 | Slovakia | 🟠 Draft legislation | ViDA transposition combined with January 2027 domestic e-invoicing reforms |
| 25 | Slovenia | 🟠 Draft legislation | Partially transpose ViDA changes applying from 1 January 2027 |
| 26 | Spain | 🟠 Government legislation | Partial ViDA transposition underway in Parliament |
| 27 | Sweden | 🟠 Bill in Parliament | 2027 reforms in Parliament |