Oct 2028 SIF VERI*FACTU approved invoicing software for all businesses
Spain looks likely to formalise a further postponement of its VERI*FACTU invoicing software requirements before the end of 2026. Hacienda announced on 5 October that it intends to move the outstanding obligations for businesses and professionals to Oct 2028, aligning implementation with the smaller-business phase of mandatory B2B e-invoicing.

The expected year-end timing is VATCalc’s assessment, based on the government’s stated plans and the approaching 1 January 2027 deadline for corporation-tax taxpayers.
Hacienda has not confirmed an adoption date, and the current 2027 deadlines remain legally applicable until an amendment is approved and published in the Official State Gazette (BOE).
Current and proposed deadlines
| Affected software users | Current legal deadline | Planned replacement |
| Corporation-tax taxpayers |
Before 1 Jan 2027 |
Oct 2028 |
| Other affected businesses and professionals |
Before 1 Jul 2027 |
Oct 2028 |
Coordination with B2B electronic invoicing
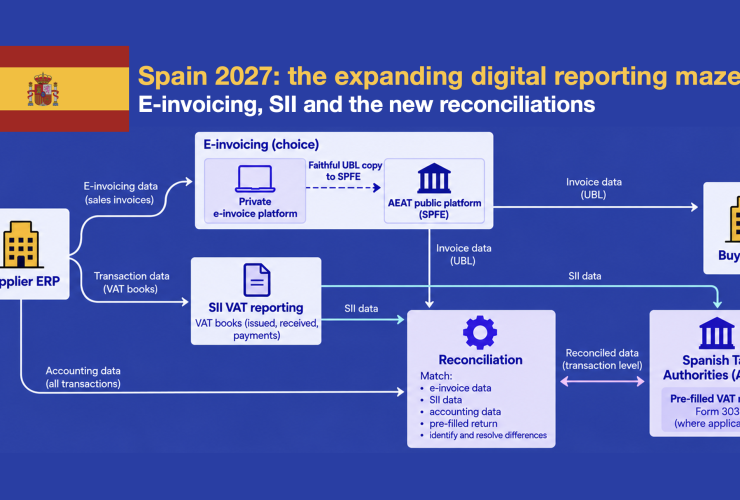
Spain’s separate B2B e-invoicing mandate under Crea y Crece applies from 6 October 2027 to businesses whose turnover for VAT purposes exceeded €8 million in the preceding calendar year. The remaining businesses and professionals must comply from 6 October 2028.
Hacienda also plans to bring the scope and certain technical aspects of the two regimes closer together, taking account of future EU VAT in the Digital Age (ViDA) reporting requirements. Existing safeguards over record integrity, retention and traceability would remain substantially equivalent.
What is being postponed
The proposed delay covers the requirement for affected businesses to use invoicing software that complies with Spain’s anti-fraud standards. These SIF requirements are established by Royal Decree 1007/2023 and Order HAC/1177/2024, and govern the software and its billing records, whether customer invoices are electronic or printed.
Systems must generate secure, linked billing records, protect their integrity and include a QR code on invoices, or its prescribed content in electronic invoices. Software producers certify compliance through a declaration of responsibility, known as a declaración responsable; prior AEAT product approval or independent certification is not required.
Which businesses are affected
The rules cover affected businesses and professionals using invoicing software, including non-residents operating through a Spanish permanent establishment for non-resident income-tax purposes. Taxpayers within SII are generally excluded, and separate arrangements apply under the Basque and Navarre foral regimes. Businesses invoicing exclusively manually are outside these software requirements.
The €8 million threshold determines the phased B2B e-invoicing timetable; it is not a general VERI*FACTU eligibility threshold. A business excluded from the software rules because it uses SII may still fall within mandatory B2B e-invoicing.
Two permitted compliance methods
- VERI*FACTU: The software automatically sends structured billing records to AEAT as invoices are issued. These records contain invoice data, rather than the full customer invoice.
- Non-VERI*FACTU: The software securely retains the records and applies additional controls, including event logging and electronic signatures on billing and event records.
Both methods can meet the invoicing software regulation. The additional electronic-signature requirements for non-VERI*FACTU systems apply to billing and event records.
Preparing for the changes
Businesses should coordinate their software review with their B2B e-invoicing plans and check which obligations apply to their operations. Until the postponement is enacted, implementation decisions should continue to reflect the existing 2027 legal deadlines